A property scheme can look highly profitable on paper yet stall because the capital stack has not been structured properly. Senior debt versus mezzanine finance is therefore not just a question of which funding is cheaper. It determines how much equity you must commit, who takes priority if the project underperforms, and how much profit remains once the scheme exits.
For UK investors and developers, the right answer depends on the asset, programme, development budget, valuation, and most of all, the credibility of the exit. Mezzanine funding can make a strong project possible with less cash tied up. Used carelessly, it can also leave too little margin for delays, cost overruns or a softer valuation.
Why the capital stack matters in property finance
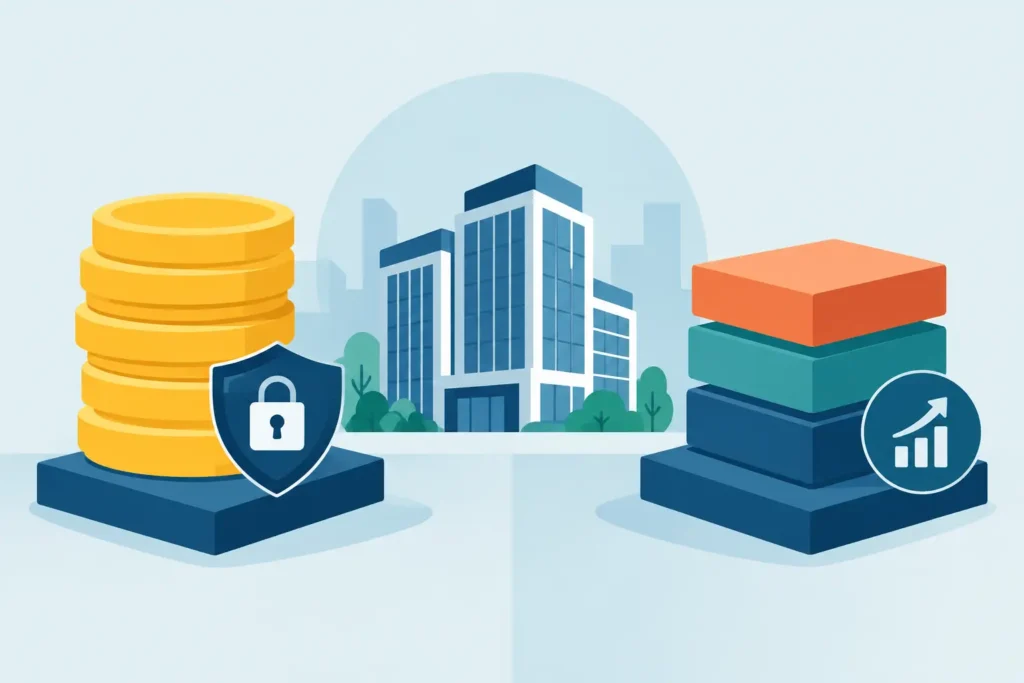
Most specialist property transactions are funded in layers. Equity sits at the bottom and absorbs the first loss. Senior debt ranks above it and is normally repaid first. Mezzanine finance sits between the two: it is subordinate to the senior lender but ranks ahead of the developer’s equity.
That ranking is central to the commercial decision. A senior lender accepts a lower return because its security and repayment priority are stronger. A mezzanine lender accepts more risk, so it expects a higher return. In exchange, it can reduce the equity required to acquire, refurbish or develop a property.
This can be particularly useful on a conversion, heavy refurbishment or new-build scheme where capital is needed before value is created. However, higher leverage does not improve a weak deal. It only changes how the risk and return are shared.
What is senior debt?
Senior debt is the primary borrowing secured against a property or development. In practice, this may be a bridging loan, development finance facility, commercial mortgage or another first-charge lending product. The senior lender will usually take a first legal charge and has first claim over sale proceeds or refinancing proceeds if the borrower defaults.
Because senior debt has priority, it is generally the lower-cost part of the funding stack. The lender will still assess the project closely. It will scrutinise the purchase price, works schedule, borrower experience, planning position, build costs, professional team, gross development value and proposed exit.
For development finance, drawdowns are often released in stages as works progress. This protects the lender but means cashflow planning must be realistic from day one. A developer cannot assume that every pound of the facility will be available immediately.
When senior debt may be enough
Senior debt is often the right fit when the lender’s loan-to-cost or loan-to-gross-development-value position leaves an equity requirement you can comfortably meet. It is usually the most efficient route for experienced investors with sufficient capital, particularly where the project has a clear resale or refinance exit.
Keeping the structure simple can protect profit. Fewer parties, lower interest costs and less complex documentation can make a material difference, especially on a shorter-term refurbishment or flip.
What is mezzanine finance?
Mezzanine finance is additional borrowing that fills the gap between senior debt and equity. It is commonly used on development schemes, larger refurbishments and commercial projects where the senior lender will not provide enough leverage on its own.
A mezzanine lender may take a second charge over the property, alongside other contractual rights. Its security is subordinate to the senior lender’s security, meaning the senior facility must be repaid first. The relationship between the two lenders is documented in an intercreditor agreement, which sets out payment priority, enforcement rights and what each lender can do if the scheme runs into difficulty.
The price reflects that greater risk. Mezzanine finance usually carries higher interest and fees than senior debt. Interest may be serviced monthly, retained from the facility or rolled up to be paid on exit. Rolled-up interest can support project cashflow during construction, but it increases the amount due at redemption and must be modelled carefully.
Some facilities may also include an arrangement fee, exit fee or a share of profit. Terms vary widely, so the headline rate alone is not a reliable way to compare offers.
Senior debt versus mezzanine finance: the real trade-offs
The obvious benefit of mezzanine finance is reduced equity input. If a developer can use mezzanine debt to replace part of their cash contribution, they may be able to take on a larger scheme or run more than one project at a time. For an established operator with a strong pipeline, that can accelerate growth.
The cost is a thinner margin of safety. Senior debt is paid first, followed by the mezzanine lender, with the developer receiving what remains. If the build runs late, costs rise or the exit value falls, the equity return can reduce quickly. In a severe downside scenario, equity may be lost altogether while debt remains due.
Senior debt also tends to come with more control over the project. The lender may impose quantity surveyor monitoring, conditions for drawdowns, limits on changes to the scheme and detailed reporting requirements. Mezzanine funding adds another stakeholder whose consent may be needed for material changes, extensions or refinancing.
The structure is not inherently good or bad. It depends on whether the additional leverage creates a sensible return after allowing for every funding cost and a realistic downside case.
A simple development example
Consider a scheme with total acquisition, build and professional costs of £2 million and an expected gross development value of £2.7 million. A senior development lender might provide £1.5 million, subject to its loan-to-cost and loan-to-GDV limits. Without mezzanine funding, the developer must contribute £500,000 of equity, plus any contingency not covered by the lender.
If a mezzanine lender provides a further £250,000, the developer’s initial equity requirement falls to £250,000. That may free capital for another acquisition or preserve working capital for unexpected costs.
But the project does not suddenly have an extra £250,000 of profit. On sale, the senior lender is repaid first. The mezzanine facility, including rolled interest and fees, is repaid next. The remaining proceeds belong to the developer. If the eventual sale price is £150,000 below forecast, or the programme extends by several months, the higher-cost layer can have a significant effect on the developer’s return.
That is why every appraisal should include a downside valuation, a cost-overrun allowance and an extension scenario. A scheme that only works at the most optimistic sales value is unlikely to be financed on attractive terms and may not be worth pursuing.
Questions to answer before using mezzanine funding
Before adding mezzanine finance, test the deal from the lender’s perspective as well as your own. Can the senior lender and mezzanine lender both be repaid from a conservative exit? Does the projected profit still justify the risk after all interest, fees and sales costs? Is there sufficient time in the facility term for planning, works, marketing and legal completion? And if the intended buyer falls away or the refinance valuation is lower than expected, what is the fallback plan?
The exit deserves particular attention. A sale exit should be based on realistic comparables, achievable absorption rates and a sensible marketing period. A refinance exit must be supported by expected rental income, valuation evidence and the likely criteria of the long-term lender. Do not assume a future lender will accept the same valuation or leverage that made the original appraisal work.
It is also vital to establish senior lender appetite before treating mezzanine as available. Not every senior lender permits it, and those that do may have specific requirements around the mezzanine provider, total leverage, documentation and payment terms. Trying to add a second layer late in the process can delay completion or lead to a full restructuring of the senior facility.
Structuring funding around the whole project
The best finance structure is the one that supports the project from purchase through to exit without putting avoidable pressure on the margin. Sometimes that means maximising senior debt and keeping equity higher. Sometimes a carefully structured mezzanine facility is the difference between passing on a good opportunity and securing a profitable scheme.
At Max Property Finance, the starting point is not simply how much can be borrowed. It is how the funding works alongside the build programme, the security, the risk profile and the exit strategy. That is the approach that helps investors protect their downside while pursuing growth.
Before committing to a highly leveraged structure, run the numbers as though the project takes longer, costs more and exits for less than forecast. If it still produces an acceptable return, the finance is supporting your strategy rather than dictating it.