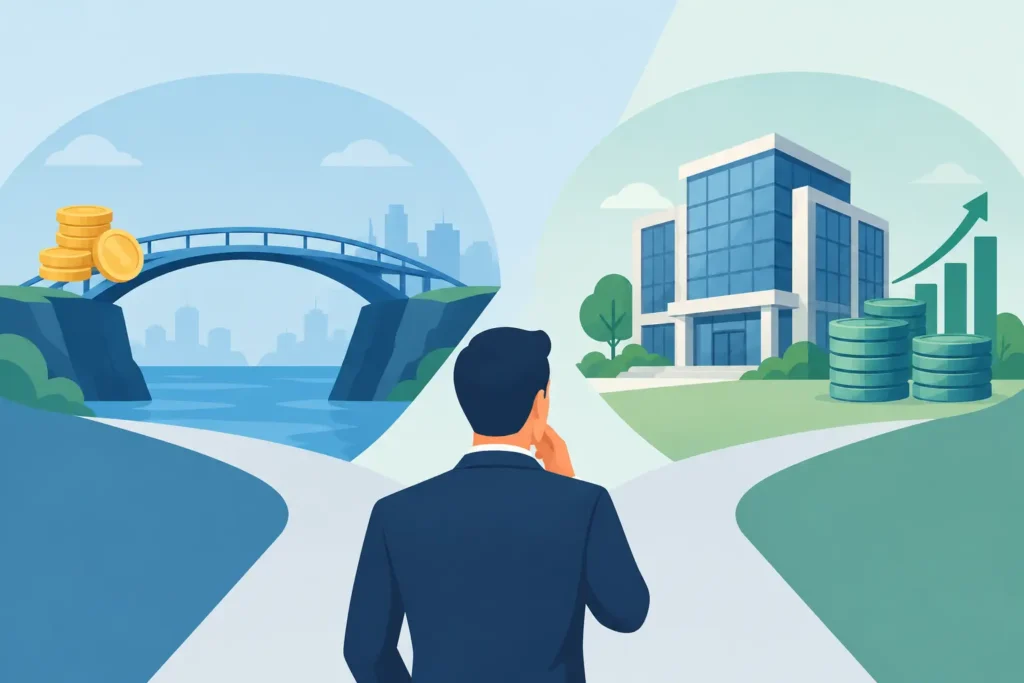
A commercial bridge versus term loan decision is rarely about finding the cheapest headline rate. It is about matching the funding period to the work required, the income the property can produce and, most importantly, the certainty of your exit. Get that structure right and finance supports the deal. Get it wrong and a profitable opportunity can become expensive long before completion.
For investors, landlords and developers, both products can fund commercial property purchases, mixed-use assets, conversions and value-add projects. Their purpose, however, is fundamentally different. A commercial bridging loan is designed to buy time and create momentum. A term loan is designed to provide stable funding over a longer holding period.
Commercial bridge versus term loan: the core difference
Commercial bridging finance is short-term, secured lending. It is commonly used to complete a purchase quickly, fund a property that does not yet meet mainstream lender criteria, carry out refurbishment or solve a time-sensitive problem. Terms often run from a few months up to 24 months, although availability varies by lender and deal.
A commercial term loan is longer-term finance secured against a business or investment property. It is generally repaid through monthly capital and interest payments, interest-only payments, or a combination of the two. The lender will place greater weight on sustainable rental income, affordability, the borrower’s experience and the long-term condition of the security.
The practical distinction is simple. A bridge helps you acquire, improve, refinance or sell. A term loan helps you hold.
That does not make a bridge a fallback option, or a term loan automatically safer. Each can be the right strategic tool. The strongest choice depends on whether the property is ready to produce dependable income today or needs work before it reaches that point.
When commercial bridging finance gives you an advantage
Speed is the most obvious reason to use a commercial bridge. A seller may require a quick exchange and completion, a distressed asset may attract competing buyers, or an auction purchase may have a fixed completion deadline. Where a conventional commercial mortgage could take too long, bridging finance can protect the opportunity.
It is also useful where the property is not immediately mortgageable. This could include a vacant retail unit, an office requiring substantial modernisation, a mixed-use building with incomplete leases, or a commercial asset in poor condition. A term lender may understandably decline until the building is lettable, income is evidenced and risks are reduced. A bridge can provide the capital to reach that position.
For value-add investors, the appeal is often the ability to borrow against a realistic plan rather than only the property’s current income. If you are buying an underperforming high street unit, improving its specification, securing a stronger tenant and then refinancing, the finance needs to accommodate that sequence.
The trade-off is cost. Bridging rates, arrangement fees, valuation costs and legal fees can be materially higher than long-term finance. Interest may be serviced monthly, retained or rolled up, depending on the lender and circumstances. A retained or rolled-up interest structure can support cash flow during works, but it also affects the total amount due at redemption and must be modelled carefully.
A bridge only works when the exit is credible. Selling the property, refinancing onto a term product, repaying from another asset sale or using business proceeds can all be valid exits. Hoping that finance will be available later is not a strategy. Lenders will want to understand the route out from day one, and so should you.
A typical bridge-to-term scenario
Consider an investor purchasing a vacant commercial building for £650,000. The building needs £150,000 of refurbishment before it can be let, and the proposed tenant will only sign once the works are complete. There is no passing rent to support a long-term commercial mortgage at purchase.
A commercial bridge may fund the acquisition and, where appropriate, part of the refurbishment budget. Once the property is improved, occupied and generating rent, the investor can refinance onto a commercial term loan. The refinance repays the bridge and creates a more sustainable cost base for the hold period.
The key numbers are not limited to the purchase price. The investor needs to test total project costs, interest, fees, contingency, rental assumptions, the expected valuation after works and the likely refinance loan-to-value. If the refinance does not clear the bridge comfortably, the plan needs adjusting before funds are drawn.
When a commercial term loan is the stronger option
A term loan is generally the better fit when the property is already stable and your intention is to hold it for income or long-term growth. Think of an established industrial unit with a solid tenant, a multi-let office building with proven rental income, or a well-let retail parade where the asset condition and leases satisfy lender requirements.
The main benefits are predictability and lower long-term cost. Rather than relying on a short deadline, you can structure repayments around rental income and business cash flow. Depending on the product, rates may be fixed or variable, and repayment terms can extend over many years.
This is particularly valuable where the property income is the backbone of the investment. A longer term can improve monthly cash flow compared with a short facility that needs clearing within months. It also allows you to focus on lease management, tenant retention and asset performance rather than arranging a refinance under pressure.
Term lending is not always slow or inflexible, but it involves deeper underwriting. The lender is likely to examine rental income, lease length, tenant covenant, property type, valuation, affordability and the borrower’s track record. If a property has a short lease, irregular income, major repair needs or planning uncertainty, the lender may reduce leverage or decline the case until those issues are resolved.
Borrowers should also check for early repayment charges, minimum interest periods and conditions around overpayments. A low rate can be attractive, but not if your business plan is to sell or refinance in the near future and the facility penalises an early exit.
Compare the full cost, not just the interest rate
The headline rate is only one part of the commercial bridge versus term loan calculation. A bridge might look expensive on an annualised basis, yet be commercially sensible if it enables a discounted acquisition, completes before an auction deadline or creates enough value to support a strong refinance. Conversely, using a bridge for a straightforward, income-producing property that could qualify for a term loan may reduce profits unnecessarily.
Assess the full funding cost against the project timeline. Include lender fees, broker fees, valuation and legal costs, exit fees where applicable, interest treatment, contingency and any lost rent during works. Then test what happens if refurbishment takes longer, a tenant moves in later than expected or the valuation is lower than projected.
The most common pressure point is the refinance. If your exit is a commercial term loan, consider its likely terms before committing to the bridge. How much rent will the property need to generate? What loan-to-value is realistic? Will the tenancy, lease length and property condition meet the proposed lender’s criteria? Building these questions into the initial appraisal is how experienced investors protect their margin.
The right facility follows the business plan
Choose a commercial bridge where time, condition or complexity prevents long-term funding today, but there is a clear route to add value and repay the debt. Choose a term loan where the asset is stable, income is evidenced and the strategy is to hold it without a looming repayment deadline.
Some projects will need both. A bridge-to-term structure can turn an overlooked commercial asset into a financeable, income-producing investment. Others need only a term facility from the outset. The difference comes down to the property’s current position, not just its potential.
Before proceeding, pressure-test the exit with the same discipline as the purchase. A well-priced building is only a good deal when the funding, works programme and repayment route all leave room for profit. Max Property Finance can help assess those moving parts early, so your finance supports the asset you are building rather than becoming the risk you are trying to manage.