A profitable refurbishment can lose momentum quickly when contractors are ready to move but the next tranche of finance has not arrived. This guide to refurbishment loan drawdowns explains how staged funding works, what lenders expect at each release point, and how to keep control of cash flow from purchase to exit.
For investors using refurbishment finance, drawdowns are more than an administrative step. They are the mechanism that turns an agreed facility into completed works, added value and a stronger sale or refinance position. Managing them well helps protect the programme, the budget and, ultimately, your profit.
How refurbishment loan drawdowns work
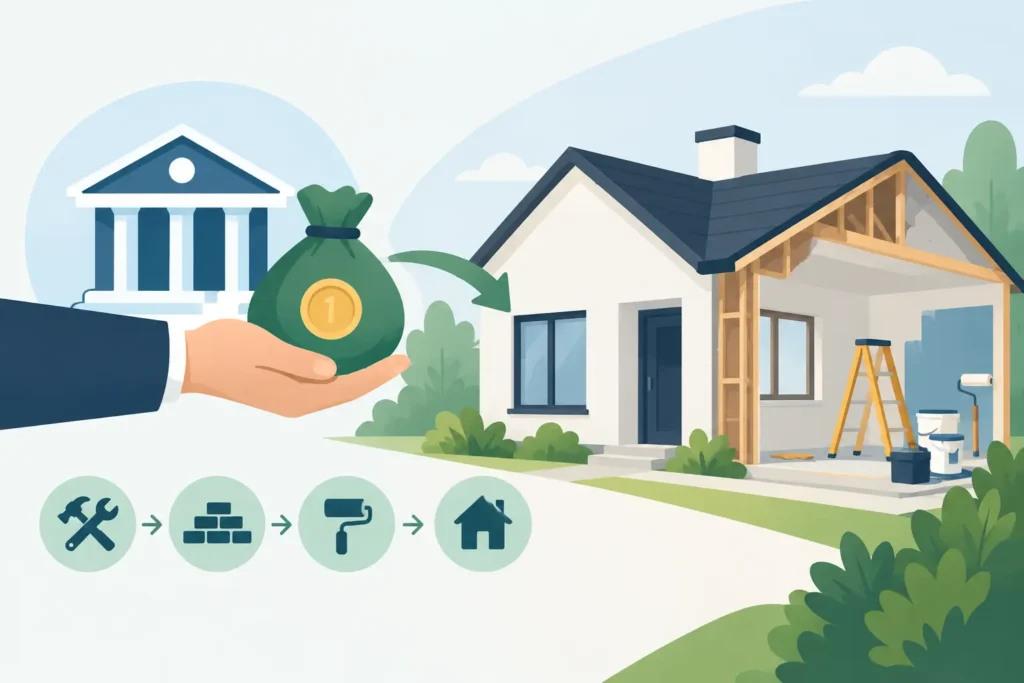
A refurbishment loan is commonly split into two elements: funds for the property purchase and a separate facility for the works. The purchase funds are usually released to your solicitor at completion. The refurbishment facility is then made available in agreed stages, rather than paid in full on day one.
These staged releases are known as drawdowns. They are normally linked to an initial schedule of works and budget submitted during underwriting. The lender may release funds after particular phases are complete, such as strip-out, first fix, second fix and final finishes. On some facilities, the lender will reimburse completed work; on others, they may advance against the expected cost of the next stage. The exact structure depends on the lender, the scale of the works, your experience and the strength of the overall deal.
This approach protects both parties. The lender can monitor that its security is improving as planned, while you avoid paying interest on refurbishment funds that are not yet required. However, it does mean a realistic programme and disciplined administration are essential.
The drawdown process from approval to release
Before completion, the lender will usually agree the total works budget, a schedule of works and an anticipated project timeline. For heavier refurbishments, a quantity surveyor may review the proposal or provide the monitoring reports. Smaller light-refurbishment projects may have a simpler process, but lenders still need clear evidence of what is being funded.
Once work has reached the required stage, you submit a drawdown request. This generally includes photographs, invoices, a brief update on progress and confirmation of the amount required. The lender then arranges an inspection, either through a monitoring surveyor or, in some cases, by desktop review. If the work completed supports the requested release and the project remains on budget, the funds are paid to your nominated account.
Timing varies. A straightforward request with complete evidence can move quickly, but do not assume money will arrive the same day you submit it. Inspections, surveyor availability, internal approvals and solicitor requirements can all add time. Build that reality into your cash-flow forecast rather than relying on the next drawdown to pay a contractor immediately.
Understand whether funds are advanced or reimbursed
This is one of the most commercially important questions to ask before accepting an offer. A reimbursement model may require you to fund labour and materials first, then claim the money back once the stage is signed off. That can work well if you have available capital, but it creates pressure where the refurbishment budget is tight.
A forward-funded arrangement can ease this burden, but it may come with more detailed monitoring or a lower initial release. Neither structure is automatically better. The right choice depends on your liquidity, contractor payment terms and how quickly you need to progress the project.
Check the lender’s monitoring requirements
Monitoring is not just a box-ticking exercise. The lender needs confidence that works match the approved scope, costs remain controlled and the eventual exit value is still achievable. On larger or more complex schemes, a quantity surveyor may flag overspends, missing work or a programme that has slipped before these issues become expensive.
Ask at the outset who carries out inspections, how much each inspection costs, how much notice is needed and whether the monitoring fee is included in the facility or payable separately. Small fees can become material when a project has several drawdowns.
Plan the budget around real site costs
The biggest drawdown problems are often created before the first contractor arrives. An optimistic schedule of works, a vague contingency or an underestimated VAT position can leave an investor unable to bridge the gap between one release and the next.
Your budget should distinguish between labour, materials, professional fees, building control costs, finance costs and contingency. It should also identify which costs must be paid upfront. Kitchen suppliers, window manufacturers and specialist trades may ask for deposits well before their work is visible enough to support a lender inspection.
A sensible contingency is not money set aside for poor planning. It is protection against the unknowns common in older properties: hidden damp, defective drainage, structural movement, outdated electrics or delays obtaining a particular material. The appropriate allowance depends on the property and scope, but a project with no contingency is rarely as profitable as it first appears.
It is equally important to consider interest. With some refurbishment loans, interest is retained from the facility; with others, it is serviced monthly. Retained interest can help preserve monthly cash flow, but it reduces the net funds available. Serviced interest demands regular payments while the property may not yet be producing income. Your funding structure should suit the project and the proposed exit, not simply offer the largest headline facility.
How to avoid delayed refurbishment drawdowns
The most effective way to keep money moving is to treat every inspection as a planned project milestone. Take dated photographs throughout the works, retain invoices and delivery notes, and make sure the site is safe and accessible when an inspection is booked. If completed work is hidden behind plasterboard or flooring, keep images that demonstrate it was undertaken.
Communication with the lender, broker and monitoring surveyor also matters. If the programme changes, explain why early. A six-week delay caused by a planning condition, utility connection or a material shortage is easier to manage when it is reported with a revised plan and credible costs. Silence creates uncertainty, and uncertainty makes lenders more cautious.
Avoid requesting more than the value of work completed or the agreed stage permits. An inflated request can delay approval and may prompt deeper scrutiny of the whole budget. Be precise about what has been completed, what remains and why the requested funds are needed.
Before your first request, make sure you can answer four practical questions:
- What evidence does the lender require for each drawdown?
- How long does inspection and payment normally take?
- Is the next release based on completed work or future expenditure?
- What happens if the scope, budget or completion date changes?
Managing changes to the scope of works
Projects change. The issue is not whether an unexpected cost will arise, but whether it can be absorbed without undermining the security, budget or exit strategy. Replacing a tired kitchen with a higher-specification kitchen may improve the finished property, but it does not automatically mean the lender will increase the facility.
If changes are necessary, provide an updated schedule of works, revised costs and a clear explanation of the impact on timing and value. Where a cost overrun can be met from your contingency or your own funds, say so. If additional finance is required, address it early. Leaving a funding gap until contractors are on site can force rushed decisions and weaken your negotiating position.
For a flip, keep the end buyer in mind. For a BRRRR project, focus on the rental demand and refinance valuation. For a commercial or heavy refurbishment, the operational viability of the finished asset may matter as much as the physical works. Every drawdown should support the original business plan rather than allowing the project to drift beyond its intended market.
Choose finance that fits the project, not just the purchase
A light cosmetic refurbishment may be suited to a standard bridging facility with a modest works allowance. A full back-to-brick conversion, structural reconfiguration or change of use will usually need a more structured refurbishment or development finance solution. Trying to fund a heavy scheme with a product designed for light works can create avoidable restrictions once construction is underway.
At Max Property Finance, we look beyond the initial loan-to-value figure. We assess the acquisition, works budget, drawdown profile, projected value and exit together, because each part affects the others. The aim is finance that supports progress on site and protects the commercial logic of the investment.
The strongest refurbishment projects are not those with the biggest budgets. They are the ones where the funding timetable, contractor programme and exit strategy all work to the same plan. Put that plan in place before exchange, keep the lender informed as the work progresses, and each drawdown becomes a controlled step towards a more valuable asset.