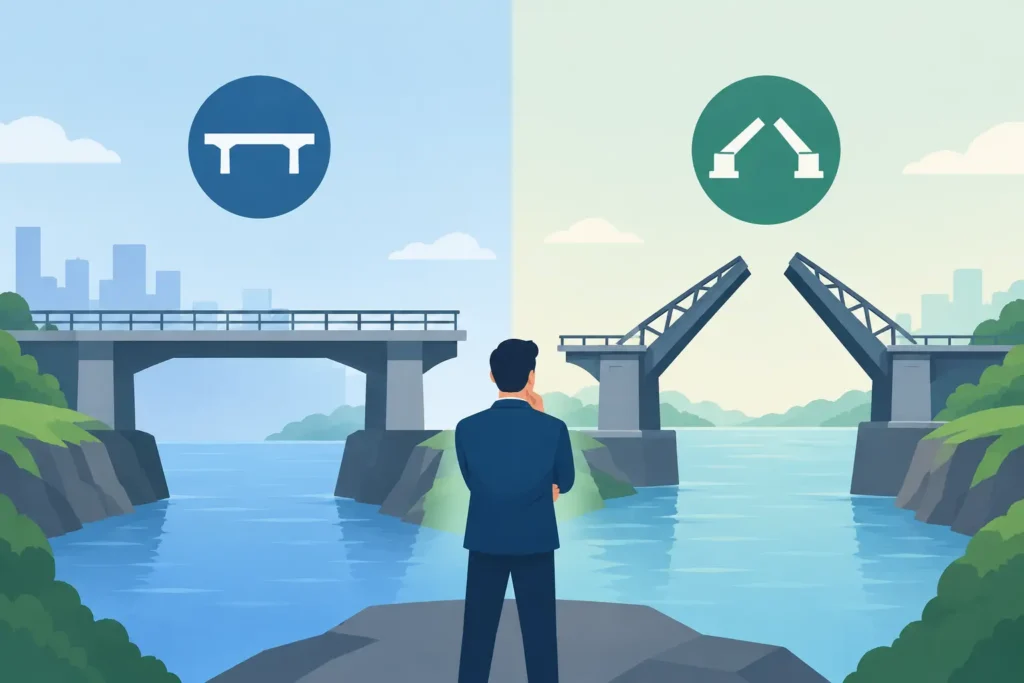
A bridging loan can secure a purchase that would otherwise be lost – but the interest rate structure can materially change the profit left in the deal. Fixed versus variable bridging is not simply a choice between certainty and flexibility. It is a decision that needs to reflect your programme, your contingency, the lender’s terms and, above all, the strength of your exit.
For an investor buying at auction, refurbishing a tired rental or converting commercial space, the wrong rate structure can put avoidable pressure on cash flow. The right one gives you clearer control of borrowing costs while you focus on delivering the project and moving into long-term finance or a sale.
What fixed-rate bridging means
With a fixed-rate bridging loan, the interest rate is agreed at the outset and remains unchanged for the fixed period or full loan term, subject to the facility terms. If market rates move upwards after completion, your monthly interest rate does not rise. Equally, if rates fall, you will not benefit from that reduction.
For many property investors, the principal advantage is cost certainty. You can model the interest bill into your appraisal with confidence, assess whether the refurbishment budget still works, and set a more reliable minimum sale price. This is particularly valuable where margins are tight or the project has several moving parts.
A fixed rate may suit a purchase with a defined programme. For example, an investor acquiring a flat in need of light refurbishment might expect works to take eight weeks, followed by a sale or refinance within six months. If the exit timetable is credible, knowing the interest cost from day one can make decisions on pricing, works and contingency far more straightforward.
However, fixed does not automatically mean cheaper. Lenders price for the certainty they provide, and the rate, arrangement fee, term and repayment conditions must all be considered together. Some facilities may also include minimum interest periods or early repayment charges, meaning a quick sale could still leave you paying more interest than expected.
What variable-rate bridging means
A variable-rate bridging loan has an interest rate that can change during the term. The mechanism varies by lender. It may be linked to the Bank of England base rate, SONIA, or a lender-specific reference rate, with an agreed margin added on top. Never assume that every variable product tracks base rate in the same way.
The potential attraction is that the cost of borrowing can reduce if the relevant benchmark falls. For an investor with a flexible exit date, or a project likely to run over its original schedule, a variable facility may offer a structure that better reflects changing market conditions. It can also be competitively priced at completion, depending on the lender and deal profile.
The trade-off is uncertainty. A rate increase can erode profit, particularly on larger loan amounts or projects with a longer expected hold. If your appraisal only works at the initial rate, you are taking more exposure than the deal may justify.
Variable pricing can be sensible where there is a strong margin, a proven exit and sufficient cash reserves to absorb movement. It is less attractive where the development appraisal is already stretched, the borrower is relying on an optimistic resale value, or refinance affordability could be sensitive to rising rates.
Fixed versus variable bridging: the commercial decision
The most useful question is not, “Which rate is lower today?” It is, “Which structure protects the economics of this project if the plan changes?” Bridging finance is short term by design, but property projects rarely run with perfect precision.
Start with the exit. If you intend to refinance onto a buy-to-let, commercial mortgage or development exit facility, test the affordability against realistic future rates, not only the rate available today. If your strategy is to sell, assess the likely marketing period, potential price reductions and legal delays. A profitable paper appraisal can quickly become fragile when interest continues to accrue for an extra three or four months.
Then stress-test the figures. Model a fixed rate over the expected term and compare it with a variable rate under at least two scenarios: no movement, and a meaningful increase in the reference rate. Include arrangement fees, valuation and legal costs, monitoring fees where relevant, broker fees, retained or serviced interest, and any exit fee. The total cost of capital matters more than a headline monthly percentage.
For example, a lower variable rate may look compelling on a six-month refurbishment loan. But if the property needs an unexpected roof repair, the buyer’s solicitor raises title queries, and the sale slips into month nine, the benefit can disappear. Conversely, paying a modest premium for a fixed rate can be good risk management where your profit depends on cost control.
The loan term and repayment method matter too
Interest rate type is only one part of the facility. The term should match the realistic project timeline, with room for sensible delay. Taking the shortest possible term to achieve a lower rate can be a false economy if an extension is expensive or not guaranteed.
How interest is paid also affects the decision. Retained interest is deducted or set aside from the loan at completion and paid to the lender for the agreed period. This can support cash flow during works, but it may reduce the net amount available for the purchase or refurbishment. Serviced interest is paid monthly, which can preserve more capital for the project but requires demonstrable income or liquidity.
Rolled-up interest accumulates and is paid on redemption. It can be useful for certain commercial or development cases, but borrowers should understand how the accrued interest affects the final repayment figure and their net proceeds. The best structure is the one that funds the entire project properly without leaving a gap at completion or an unrealistic burden during the term.
When fixed rates are usually the stronger choice
Fixed bridging often suits borrowers who value certainty more than the possibility of future rate reductions. This includes investors working to a tight refurbishment budget, first-time developers managing a defined build programme, and landlords who need a reliable figure while arranging a refinance.
It can also be appropriate where a property has complications that may extend the timescale: planning conditions, lease issues, vacant possession, complex title matters or a non-standard construction. The rate will not solve those problems, but predictable borrowing costs can give you more control while they are resolved.
A fixed structure is particularly worth considering if you are highly leveraged. The more the scheme relies on borrowed money, the more sensitive the profit can be to a shift in interest costs. Certainty has a commercial value when it protects your downside.
When variable rates can make more sense
Variable bridging may be a good fit for experienced investors with substantial equity, a quick and well-evidenced exit, and flexibility in their project budget. It can be attractive where the loan is likely to be repaid early and the facility does not impose costly minimum interest or repayment conditions.
It may also suit a borrower who expects rates to reduce and can comfortably withstand the alternative. That last point matters. A view on the market is not a financing strategy unless the numbers remain viable if that view proves wrong.
For repeat investors, a variable structure can sometimes align with a portfolio approach, where cash reserves, multiple exits and strong lender relationships provide greater resilience. Even then, every property should be assessed on its own merits. A short-term loan on a straightforward auction purchase is very different from funding a heavy refurbishment with planning risk.
Questions to settle before accepting terms
Before proceeding, establish exactly what the rate is, what it is linked to, and when it can change. Confirm whether there is a minimum interest period, an exit fee, extension fees or early repayment charges. Ask how retained, serviced or rolled-up interest will be calculated and whether the gross facility is sufficient once all deductions are made.
You should also be clear on the lender’s view of the exit. A bridging lender will want evidence that your sale or refinance plan is credible, not merely possible. That may include comparable sales, rental evidence, a mortgage decision in principle, planning documentation, a schedule of works or proof of funds.
At Max Property Finance, we assess the full deal rather than chasing the lowest advertised rate. The aim is to arrange funding that supports your purchase, your project timetable and your planned profit – while giving you a realistic route out of the bridge.
The strongest bridging decision is rarely the one that looks cheapest on day one. It is the one that leaves enough margin, enough time and enough certainty to execute your strategy well.