A development facility can look generous on paper, but the amount available is not the same as the cash you can use this month. Development finance drawdowns control when funds are released, and getting them wrong can leave a perfectly viable scheme short of working capital at the point momentum matters most.
For UK developers, drawdowns are not an administrative detail. They affect contractor payments, programme certainty, interest costs and, ultimately, the profit left in the project. A well-structured facility supports the build as it progresses. A poorly understood one can create avoidable delays, equity pressure and difficult conversations with contractors.
What are development finance drawdowns?
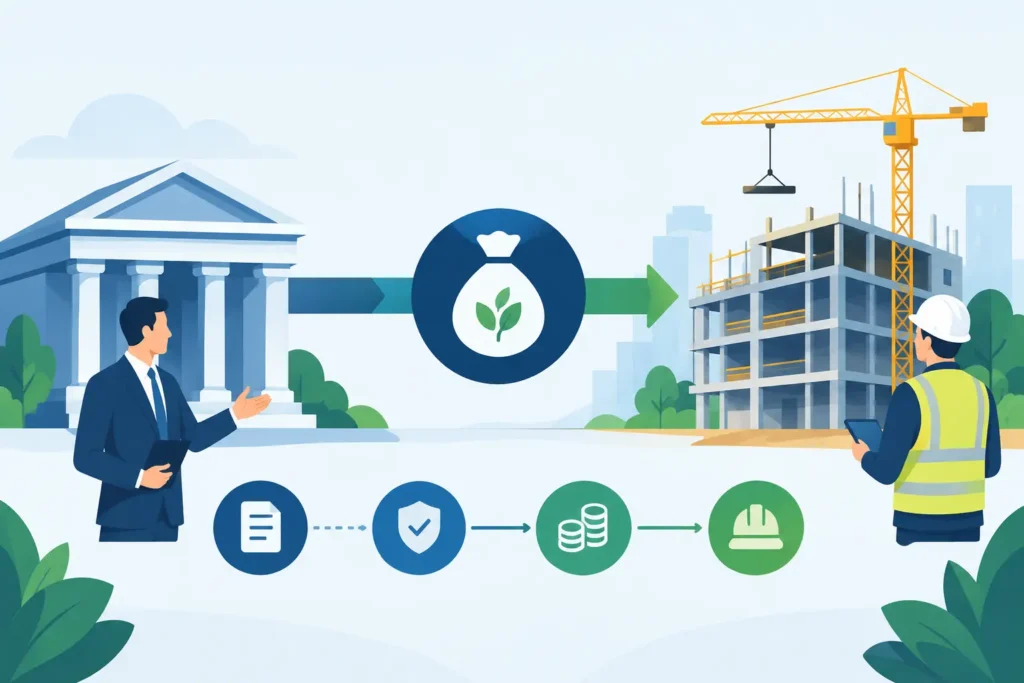
A drawdown is a release of money from an agreed development finance facility. Rather than advancing the entire loan on day one, a lender releases funds in stages as the project reaches defined milestones and expenditure is evidenced.
Usually, the first advance is used to acquire the site or property. The remaining loan is allocated to construction costs and released through monthly or milestone-based drawdowns. The lender wants to see that work has been completed, the project remains on budget and the security is becoming more valuable before advancing further capital.
This protects the lender, but it can also protect the developer. Regular monitoring forces attention on cost control, programme management and the remaining contingency before a small overspend turns into a funding gap.
The exact structure depends on the scheme. A light conversion may have fewer drawdowns than a 20-unit new-build project. Some lenders work to fixed stages, while others assess actual progress each month. Neither approach is automatically better. The right option depends on the complexity of the works, the contractor arrangement, the build programme and how much flexibility you need.
How a typical drawdown process works
Before completion, the lender agrees the facility amount, loan-to-cost and loan-to-gross-development-value limits, build budget, programme and drawdown schedule. These documents matter because they set the framework the monitoring surveyor and lender will use throughout the project.
At completion, the lender normally releases the initial advance. On an acquisition and development facility, this may cover a percentage of the purchase price, associated approved costs and sometimes part of the early works. The developer contributes the balance, including any equity requirement, fees, taxes and costs that fall outside the agreed facility.
As construction progresses, the developer submits a drawdown request. This typically includes an updated cost report, invoices or evidence of expenditure, photographs, programme information and a forecast of costs to complete. A monitoring surveyor, often appointed by the lender, then inspects the site and assesses progress.
The surveyor is not simply checking whether walls have gone up. They are considering whether completed works support the claimed value, whether the project is on programme, what has been spent, what remains to be spent and whether the contingency is still adequate. Their report informs the lender’s decision to release the next tranche.
Once approved, funds are paid to the borrower or, in certain structures, directly towards agreed project costs. Allow for the inspection, report and lender approval process in your cashflow. Drawdowns are rarely instant, particularly where information is incomplete or a valuation issue needs clarification.
The numbers lenders monitor closely
Development funding is built around forecasts, but lenders make drawdown decisions using evidence. The most important figure is often the cost to complete. If the surveyor believes the remaining works will cost more than the undrawn facility plus your available equity, the next draw may be reduced or held back.
Lenders also monitor loan-to-cost. This compares total borrowing with the purchase price and build costs. They will separately consider loan-to-GDV, which compares borrowing with the expected completed value. A scheme may work at the outset but move outside the lender’s acceptable parameters if costs rise or the projected sale values soften.
Cashflow deserves equal attention. Your contractor may require payment before the lender’s valuer has inspected the relevant work, while professional fees, utility costs and planning conditions may arise outside the main construction schedule. Interest, monitoring surveyor fees and lender fees also need to be included in the funding appraisal. Assuming every project cost will be reimbursed immediately is a common and expensive mistake.
Why the valuation and monitoring report matter
Many developers focus on the gross development value at the end of the project. In reality, the monitoring surveyor’s view during the build can have a greater short-term impact on liquidity. If progress is behind programme, workmanship is unsatisfactory or costs appear understated, the lender may advance less than requested until the position is resolved.
This is not always a sign that the lender has lost confidence in the scheme. It may simply mean the evidence does not yet support the requested release. The practical response is to provide clear documentation, answer queries quickly and show a credible plan for any variance.
Experienced developers treat the monitoring surveyor as part of the project’s funding infrastructure. Provide current cost reports, notify them of meaningful changes early and make sure they can access the site safely. Surprises tend to slow decisions. Clear reporting gives the lender greater confidence that the development remains controlled.
Common pressure points in development finance drawdowns
The first is a mismatch between the build programme and the drawdown schedule. A contractor’s package may require substantial early expenditure on foundations, steel, materials or deposits, yet the lender’s staged releases may be weighted towards visible progress later in the build. This creates a cash shortfall even where the total facility is sufficient.
The second is underestimating soft costs. Planning obligations, building control, warranties, professional fees, connection charges, marketing and finance costs can place real pressure on cashflow. Some may be fundable, but only if they are included and agreed in the original appraisal.
The third is treating contingency as spare profit. Contingency exists because projects change. Ground conditions, specification amendments, labour availability and delays can all affect costs. If it is used casually in the early stages, there may be no buffer when a genuine issue emerges.
Finally, developers can be caught out by exit timing. A development loan is usually short term, and interest continues to accrue while units are being sold or refinanced. A sensible appraisal tests a slower sales period, a lower-than-expected valuation and an extension requirement. The aim is not to make the deal look pessimistic. It is to ensure it still works when conditions are less favourable than the best-case spreadsheet.
How to keep drawdowns moving
The strongest applications for a drawdown are prepared before the lender asks. Keep a live development appraisal that separates committed costs, paid costs, outstanding liabilities and forecast costs to complete. Reconcile it against the original budget each month, rather than relying solely on the contractor’s valuation.
Maintain a rolling cashflow forecast that shows when money must leave the business and when you realistically expect each drawdown to arrive. Build in time for a site inspection, report production and lender processing. If a major payment is approaching, raise the funding conversation early rather than hoping a request will be turned around immediately.
It also pays to agree decision-making authority with your contractor. Variations should be priced, recorded and assessed for their impact on the programme and remaining contingency before work proceeds where possible. A series of small unrecorded changes can become a material overspend by the next monitoring visit.
For more complex schemes, a quantity surveyor or experienced project manager can add significant value. Their cost reporting can give you, the monitoring surveyor and the lender a clearer basis for decision-making. The additional professional cost needs to be justified, but on a sizeable development it can help avoid far more costly funding disruption.
Choosing a facility that matches the scheme
The headline rate is only one part of a development finance decision. Ask how the lender calculates each drawdown, whether interest is retained, what evidence is required, how monitoring fees are charged and what flexibility exists if the programme changes. A cheaper facility with slow, inflexible releases can be more expensive in practice if it forces you to inject unplanned equity or delays the build.
Your exit should shape the facility from day one. A developer selling completed units needs sufficient time for marketing and sales. An investor refinancing onto buy-to-let or commercial debt needs to understand the likely completed valuation, rental evidence and refinance criteria well before practical completion.
Max Property Finance approaches this from the investor’s side as well as the lender’s: the funding structure must support the commercial plan, not merely meet a lending formula. When the drawdown schedule, cost plan and exit are aligned before completion, you are in a stronger position to keep the site moving and protect the profit you set out to make.
Before exchanging contracts, stress-test the timing of every major payment against the proposed facility. That single exercise often reveals whether a development loan is genuinely fit for your project or simply looks attractive in a headline quote.